How and When to Follow Up

As we’ve discussed, you follow up quickly on an agreed-upon date at an agreed upon time. If you reach voice mail or an assistant, you simply say, “I’m calling as promised.” If you have a trusting relationship, the buyer should have you on the calendar and take your call. If the buyer has encountered an unavoidable conflict, then the buyer should call you back promptly. 

That’s the best of all possible worlds, a Candidian outcome. Your inquiry should then be an assumptive closing statement, such as: 

Which option have you decided to implement?
Which payment option do you prefer?

If for any reason you have not set a definitive time and date with the buyer, then my advice is to contact the buyer 24 hours after receipt of the proposal. If you’re using FedEx you can track that and actually see who signed for it and when (anticipating the possible reaction, “Did we get it?”). Always do this by phone, never e- mail. Consultants are afraid to use the phone, I think because the possible rejection is starker than by e-mail. Get rid of that mind-set. Pick up the phone and call. 

My general rule for any unreturned communications is three tries and a letter. That means that after three calls, you send a hard copy letter (avoid getting lost in e-mail) and say the following: 

I’m sorry we couldn’t make contact. I’m here if you need me, but I certainly don’t want to hound you. After three attempts, I’m respecting your privacy but am happy to continue when you’re ready. 

When people don’t get back to you it’s not because they’re busy, it’s because they’re rude and unprofessional. (This is much more common at lower levels and within HR than with executives, by the way, who have no need to create artificial power in this manner by being non responsive.) It’s passive/aggressive behavior that is detestable, so don’t throw good time and money after bad. However, you needn’t burn bridges. My two lines above are polite and leave the bridge intact. 

It’s always a good idea to cultivate a relationship with the buyer’s secretary, assistant, or key subordinate during your visits if possible. You can then call them and say: 

I need your advice. Is she in town and, if so, what’s the best time to reach her? Can you put me on her calendar? 

The old bromide works well here: Call early in the morning or after hours. Many buyers are at their desk by 8 and still there at 6, with their line open because their assistant isn’t there and they may be expecting calls (though not yours!). 

If the buyer does take the call as planned, and responds, “Option 2, we’ll send the 50 percent deposit tomorrow, when can you start?” then simply move forward. You may say: 

Thank you, I’m looking forward to our partnership. Will you use the invoice and FedEx envelope I enclosed, or will you need something else? (Some firms need to give you an accounts payable number or require proof of malpractice insurance coverage, and so forth.) While I have you on the phone, let’s get everything squared away. How is Tuesday morning to start? Can you and I meet for 30 minutes? 

If at some later time, accounts payable or a similar function has someone contact you to inform you that the provisions of your proposal are out of policy, or that they intend to pay you 60 days, net, or that you’ll have to jump through other hoops, simply go back to your buyer and emphasize the terms and conditions that were accepted in your proposal. Don’t argue with bureaucrats, that’s all they have to do. Let your buyer do the heavy lifting. 

Some firms (especially overseas) will want to wire funds. Make sure that they have your international routing (SWIFT) number, your account name and number, your bank’s name and address, and a management contact at the bank. In my experience, wired funds take from 3 to 10 days to reach your account once initiated by the client. 

Do not accept foreign currency checks, no checks in U.S. funds drawn on a non- U.S. bank. The bank will return it, via normal mail, to get their exchange and will charge you a fee for taking so long to do it. U.S. funds must be drawn on a U.S. bank. Most foreign banks have U.S. counterpart relationships.

Case Study: Purchasing Problem 

After I had reached a deal with Tom, the general manager, I was to start in two weeks. In the interim, Peggy called me from purchasing to inform me that Tom “wasn’t authorized” to conduct negotiations with “vendors.” “I’m a consultant, not a vendor,” I pointed out. 

“You’re a vendor to me,” she sniffed. Then she told me that I was to provide an hourly rate, and if it was more than 10 times higher than the average of the last six consultants who worked there, I would have to lower it. “You’ll do that or you won’t work here,” she said. 

“Good-bye,” I said. 

I called Tom and he told me he had heard about such things, and that he’d take care of it. He had Peggy fired.

I have no remorse. Her job was to support the line executives, not to play traffic cop. I realized that arguing with her was a losing proposition, and that I had no intention of losing in the end. 

Accept credit cards when the client requests it. The fees you’ll have to pay (generally from 2 to 3.5 percent) are a cost of doing business. On a $30,000 fee, that’s about $900, which is worth it to get the money in your account quickly. 

In most cases, you’ll get through to your buyer and he or she will choose an option to proceed. Life being what it is, other things can occur. So let’s take a look at what you can reasonably anticipate getting in the way and how to cope. 
What to Anticipate and How to Cope

I mentioned earlier that my “hit rate” with this process is about 80 percent, though some people in my Mentor Program report upward of 90 percent. In any case, that means that about 60 percent of the time I simply get a yes, 20 percent I have to cope with “issues,” and 20 percent I simply don’t get the business.

Bad things happen to good people like you and often me. You can anticipate some and cope with them or even resolve them. 1. The client loves an Option 3 facet but cannot approve expenditures above Option 2.

In this case, technically there is another buyer just for Option 3, because you’ve exceeded your buyer’s grant of authority with it. But it makes no sense to try to move to that more senior person when your buyer is ready to proceed. Nor does it make sense here to cavalierly say (as I often do suggest to those buyers who have the money but want to see if they can get a “deal”), “Well, that’s why we have Option 2.” 

You can’t just grant Option 3 at Option 2 fees because the next question is, “How low will you go?” Perhaps to Option 1 prices? 

But what you can do is to move things around. Suggest that you can move one facet from 3 to 2 at a slightly higher price or, if possible in the context of your options, take some things out of 2, move something from 3 in, and simply charge the Option 2 fee. It helps to be flexible in these cases if you believe your buyer simply doesn’t have the ability to invest more. But you must show that you’re removing something, not just lowering the fee. 

2. The client can’t approve a check over a certain amount even though the buyer has a budget for more than the total amount. 

It’s often the case that the buyer has a $500,000 budget, for example, but can’t approve checks over $150,000 without another officer’s approval or a committee review. That can be deadly, because people without any interest in or appreciation of the project will feel it their earthly calling to question the amount being invested. 

The best way to cope with this is to suggest that the buyer authorize more than one check at his or her grant of authority until the full amount is paid. This may re- quire that you change the terms of payment or that time frames be extended or work protocols shifted. You’ll find a case study earlier in the book where this exact issue arose and was handled in this manner. 

You do not want your proposals going to the legal department or to executives who have not participated in the process. So suggest this alternative to your buyer. (Many will suggest it to you.) 

3. Your buyer says something to others that threatens the project. 

Rehearse with your buyer if for any reason other high-level people need to be apprised of the work that’s to come prior to the proposal being signed. I’m not talking about further approvals, which means that you haven’t been speaking to the real buyer. But often there are executive councils or senior committees of which your buyer is a member and on a regular basis they inform each other of changes in their operations so that others can copy best practices or adjust to new ones (which is actually a pretty good idea). 

But your client should not mention details of the proposal, merely the results expected of a new initiative. Ideally, the buyer shouldn’t even mention you. But coach the buyer: For example, tell the buyer asked about the cost to simply say the proposal hasn’t been reviewed yet although it should clearly be well within budget. This will help you avoid an inadvertent creation of some other interested but unhelpful parties. 

4. The buyer gets cold feet. 

This is the reason that I urge you to act speedily and with all due haste. You want to strike while the buyer is still warm in the glow of your agreement. But, stuff happens. 

The causes can be legion, and we’ll deal with legitimate, last-minute objections below. They can include an unexpected event, a random comment by a superior, fear expressed by a subordinate, even a misunderstanding by you or the buyer that emerges when the buyer sees everything in writing. 

Case Study: The Careless Comment 

One of my Mentor Program Members in a European country had the equivalent of a $2 million project approved by the COO, who had budget and responsibility for such things. However, before it was signed, a board meeting was scheduled and the executive had to appear and report on new developments. He invited my colleague to observe the meeting as a courtesy. 

This particular board included two members of the union, per the contract. At the conclusion of the COO’s report, another board member casually asked what the price was, and the COO told him. The two union members immediately came to attention and suggested strongly that the matter be studied, given the immensity of the fee. The chair had no choice but to agree. 

My colleague was told two days later that the project was dead. For all of his preparation, he had never rehearsed with his buyer what to say if asked about the fee.

Follow up your proposal quickly. If you sense any hesitancy, confront it at the time, not later. In other words, if the buyer says, “I looked it over and things seem just as we agreed, but I’d like to. . .” then ask immediately why he or she feels it necessary to talk to others, to take a few more days, to compare it to the strategic plan, and so forth—whatever it is that finishes that sentence above. Don’t hesitate.

Before you leave the buyer with conceptual agreement attained, always ask, “Is there anything you can think of that would be an obstacle to us working together once you see the proposal and the investment levels provide for dramatic return?”

Try to ferret out what you can at that point. But if you encounter this when you make your follow-up call, confront it: “I’m not sure why that would help in any way, and I’m concerned that you may see obstacles that we hadn’t discussed. Please tell me what, specifically, gives you cause for pause at this point?”

Don’t be afraid to do this. The longer the buyer takes, the more bad things can happen. The faster the decision, the faster the best thing happens.

Overcoming Last-Minute Objections

There are legitimate objections that arise at the last moment, along with not so legitimate ones. There really are no objections you haven’t heard before, so it’s negligent not to be ready for all of them. You may not win every battle, but you should give a good fight. 

Last-minute objections fall into these four categories: 

1. Genuine misunderstandings.
2. Legitimate intervening events.
3. Resistance encountered from others.
4. Illegitimate fears.

1. Genuine Misunderstandings 

The buyer may have said that sales could be improved by 15 percent, but the client meant over two years and you thought it was over a single year. Hence, the returns may seem overly optimistic in your proposal. Or you may have said that your company would run all focus groups (meaning subcontractors or employees you routinely utilize) but the buyer thought that you, personally, would conduct them all. These things happen in all business meetings and there is no malice or incompetence involved (unless they repeatedly happen to you). 

The cure here is to ask the buyer what would make him or her happy, and see if you can accommodate that. Compromises are fine. You want to try to avoid lowering fees. For example, lowering the return to the first two years rather than the first year is not so debilitating, and may mean a 14:1 return on investment the first year instead of 20:1, which is still impressive. And it may be possible for you to agree to do half the focus groups or personally conduct interviews or convince the client that your people are better at focus groups than you are, which is why you have them conduct the sessions. No harm done. 

Take the responsibility for all misunderstandings, whether your fault or not, and try to preserve your fees by offering compromises or showing the buyer that there’s nothing to fear. 

2. Legitimate Intervening Events 

A company plant blows up. (It’s happened to me.) The buyer’s boss is fired, or re- placed, or leaves on extended disability. There is a purchase or divestiture announced. A company employee is kidnapped overseas. There is a major technology crash. A competitor gains a huge leap. 

These things happen regularly, so the odds are that they will happen in between the submission of your proposal and its acceptance at some points in your career. 

Be prepared. 

My recommendations: 

  • If you hear through other channels, phone your buyer immediately. If your buyer tells you, then suggest that you immediately confront the issue. 

  • My favored alternative is to suggest that the causes and reasons for the project haven’t actually been changed by anything that has transpired. So there really is no good reason to stop, just as there is no reason for the organization to suddenly stop doing business. 

  • If the change is too severe for the project to persevere, suggest to the client that you reorient your work within the budget of the first proposal (and options) to help with the issue at hand. The buyer has designated time, money, and you, so why not capitalize on those resources to at- tack the new challenge? 

  • If the first two don’t work, force the buyer to agree to a specific date to talk again to review the status. Remind the buyer that the current terms and conditions are good for 90 days only. (Some consultants actually put time deadlines in their proposals. I don’t because I want to encourage clients to act immediately and not believe they have a 90 day window.)

3. Resistance Encountered From Others 

On many occasions, others will know of the pending project and proposal. Monies may have been budgeted, people’s opinions sought, a gaggle of consultants brought in, and so forth. Some of those people want to undermine proposals be- cause they are threatened by the intervention. 

The best preventive action for this is to apprise your buyer in advance of this likelihood. (This is especially important if you’re asked to chat with subordinates by the client.) Tell the buyer that people tend to be threatened or offended that they aren’t called to take the lead internally on such projects. 

If the resistance still arises, suggest to the client that there are two options:

1. Co-opt the resistance. The buyer can talk to those involved and ensure them a role (and credit) in the implementation aspect.

2. Overwhelm the resistance. Tell them it’s a fait accompli and they had better get used to it, because they’re all expected to float on this boat.

Finally, point out that the decision is strategic, appropriate for the buyer, but not for people who are the tacticians and implementers. Sometimes tough decisions are required to effect the greatest positive change. 

4. Illegitimate Fears 

Your buyer and those around him may fear the following:

  • The unknown
  • Failure
  • Embarrassment
  • Bruised egos
  • Significant change
  • Going “public” with a new initiative
  • Risk
  • Fear itself

Fears aren’t uncommon, but these I call “illegitimate” because they really shouldn’t derail a significant buyer oriented toward improving his or her operation. The recipe for dealing with this is simple: Isolate the actual fear from my list above (it’s not all of these, after all); then ask what is the worst that can happen; demonstrate that you have preventive actions in place as well as contingencies; and point out that any new venture entails some degree of acceptable risk.

So if embarrassment is the issue, demonstrate that continued performance at the current level without any visible attempts at improvement is much more embarrassing, and that even modest improvement would look very good, and that the two of you are prepared to handle whatever arises through additional training or a slower pace (the benefit of value-based fees).

It’s darkest just before the dawn. 

Overcoming Legitimate Obstacles

There are legitimate obstacles that arise even at this late juncture, which is why “hit rates” aren’t even higher with this system. But you can maximize your rate of acceptance if you prepare for the common causes of last-minute interference. 

Obstacle 1: The buyer is called away. 

There have been more occasions than I thought possible in the realm of probability where my buyer has suddenly “vanished.” There’s an emergency in Puerto Rico and the buyer must rush to San Juan. There’s a sudden vacancy in the executive ranks, which the buyer must fill. There’s a potential client defection and the buyer must hurry to shore up the relationship.

Personally, the buyer is called away by illness in the family, a birth, a death, an accident, and so forth. 

You certainly don’t want to intrude in a moment of grief or even celebration, but you do want to be resolute on lesser business issues that suddenly impose them- selves. Consequently, here’s what to do when you achieve conceptual agreement in person and before you begin to write the proposal. 

  • Inform the client that sometimes either of you can be suddenly co-opted.

  • Suggest that you therefore exchange private cell phone numbers and e-mail addresses if you already haven’t.

  • Agree that a backup plan will be to talk in the evening or on a weekend should a sudden unforeseen issue arise.

Then follow up quickly as I’ve recommended throughout the book before bad things begin to happen to good people who wait. 

Obstacle 2: The buyer’s boss becomes involved. 

In large organizations, most of your quite legitimate buyers will have quite legitimate superiors. (In small businesses, you’ll find the owner often “reports” to a spouse.) Even though the superior need not provide approval or budget, there are times when your buyer may deem it politically correct to mention the project. 

This becomes a problem because none of the underlying value has been established with the superior, and you have no relationship or credibility with the superior. In larger projects, the buyer’s boss may reasonably say, “That’s a substantial in- vestment. Are you sure it’s the best approach?” And with that simple, reasonable question, the buyer may say, “I do, but if you have other ideas. . .” out of a sense of primal survival need. 

In the light of such a possibility: 

  • Ask the buyer if any of his or her superiors need to be apprised or involved prior to sending the proposal. Offer to meet with them at any time.

  • Suggest to the buyer that the contents of the proposal are heavily dependent on the intimate understanding and collaboration achieved by the two of you, and others may not appreciate the value and ROI but merely look at price.

  • Ask if there is anything at all you can do to help with internal acceptance if that’s an issue.

  • After the fact, urge the buyer to introduce you to any inquiring parties because “It’s unfair for you to market my abilities and approaches, and I can’t allow you to be in such an awkward position.”

Obstacle 3: The buyer and/or you have erred. 

Sometimes the buyer has believed that some assumptions are facts (i.e., turnover rates or average sales amounts). Sometimes you will be in error on your projections (the percentage increase in sales expected will be only in two areas, not all five). These errors are discovered after the buyer reads the actual proposal, which is really why you’ve submitted it and the buyer is reading it! 

At this point it may seem obvious to merely correct the errors and resubmit the proposal, and that is what you would do. However, you may be doing so with far less value than originally estimated and therefore less ROI, consequently too high a fee. So here are ways to avoid those unpleasantries in case their ugly heads arise: 

  • Always maximize the value statements from any one objective. Example: The simple objective to increase profits could generate impact (value) including increased investor attraction, better retention of top talent, higher investment in R&D, and larger bonuses.

  • Stress that you’re taking the low end of the range of possible value, or cutting estimates in half. Be very conservative, to demonstrate that there is the potential for much more.

  • Maximize the number of objectives in the proposal, which may include revenue, profit, stress reduction, higher visibility, more productivity, less cost, and so on.

  • Ensure that you have three solid options, the least of which provides strong value.

  • Stress in objectives and value the personal, emotional impact that will be achieved for the buyer. 

In providing for these elements, you can go back to the buyer after errors are  discovered and point out that there is still huge value and ROI; that a lesser option may now make sense; that the errors are inconsequential; and so forth. You don’t want to have to rewrite your proposal but merely have the buyer see that the return may be 12:1 instead of 17:1, or that the emotional gains are still quite present, and that there’s no point in making any revisions. 

“Bad” things can happen, often suddenly, but their simple occurrence shouldn’t be cause for despair or to give up the ship. Some, as you can see, are preventable if you take the right actions early. Others can be dealt with on a contingent basis if they do occur. But the key is that there are things to do, actions to put in place that can minimize this not infrequent stalling point. 

It’s a shame to have proceeded this far only to let anything less than a natural disaster get in the way of the value you’re capable of delivering to your client. Hence, it’s incumbent on you to deal with the rapids that sometimes abruptly appear downstream. 

Creating a Signature (or Something Else)

The point of all this planning and preparation is to get a signature on the bottom line of the proposal (my ninth category, “Acceptance”), because my proposal for- mat includes the buyer’s acceptance and there is no legal contract beyond this document (we’ll talk about legal documents and departments in the next chapter). 

So how will that happen? 

The most basic and fastest route is for the buyer to choose the desired option, sign and date one copy of the proposal, and return it. This is why the two copies I send are both executed by me. I don’t want the buyer to sign, then return it for me to sign, then return it to the buyer again. Too much time, too much potential for bad things to happen to good people who wait. I also include a FedEx letter envelope already addressed to me by using my account, and an invoice that can be used for any of the options and/or for full payment discount and “normal” 50 per- cent deposit.

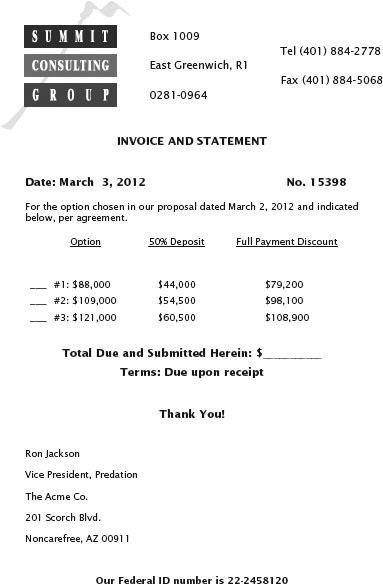
The invoice would look like the one shown in Figure 6.1. You’ll note that this can be hard copy or electronic, and I send them in both forms. My federal ID numberis on the invoice because many company payment departments demand it, and I don’t want them to have to contact me (usually in 30 days!). Also, it’s called “Invoice and Statement” because some firms demand one or the other, so I’m covering all bets with a single document. 

FIGURE 6.1 Invoice and Statement 

Specify the funds if you’re billing a nondomestic firm or wire instructions. You may also provide directions for wire transfer or credit card payments, depending on the situation. I tend not to provide these unless the client has re- quested them, because credit card payments entail interest charges on your part (3 percent on $121,000 is $3,640, for example, and wire transfers also result in a bank charge to you; both modes require up to a week before the deposit clears). If the client needs these alternative payment devices I’ll do it, but I’d rather not. As it is, checks take a few days to clear and checks not drawn on a domestic bank involve long delays and exchange charges.

Thus, ideally, the buyer signs the proposal copy that will be returned, chooses the option and payment terms, fills in the invoice, has a check issued, inserts the three items in your FedEx envelope, and you have it all the next day. 

Sometimes, however, it’s not so easy. 

If the buyer says, as often happens, “I want to begin, but the check cycle here is 60 days,” you don’t have an inconvenience, you have a problem. First, any buyer can have a “manual check” drawn, which is simply a computer check that pops out immediately. That’s because “60 days” means that your invoice is sitting on some- one’s desk in procurement or accounts payable for 59 days. 

So you reply, “If that’s the best we can do, I’ll plan to start in two months.” A deal is a deal, and if you’ve managed to “consultant up” and be a peer of the buyer to this point, don’t cave now. You’re partners, not buyer/seller. The buyer will usu- ally say, “Let me make a call.” 

Attack any issues like this as partners: How do we resolve this? 

Having said that, there are times when you want to begin immediately so the hastening of a signature or reasonable facsimile is important. 

For example, the buyer may well call you or respond when you call the buyer a day or so later, “I love this, Option 2 it is, and we have a rare chance to involve all of my country managers at once because they’re here this Friday for a conference. Can you come in to meet them and get acquainted? It will help tremendously when you have to talk across long distances later.” 

The answer to this is, “Of course,” as long as your schedule actually permits it. I call this “pouring cement on the sale,” because once you’re on-site working there is virtually never a retreat on the buyer’s part. You simply add, “The proposal calls for payment on commencement, and this is quicker than either of us anticipated, but I’m happy to help. Can you expedite the payment?” 

A “telephone handshake” is always good enough for me. If the buyer says, “Go,” I start moving. Don’t forget that the Acceptance aspect of the proposal says, in effect, “your payment is as good as your signature.” So if you get the check, simply ascertain which option, which you should readily tell by the amount, and get cracking. 

The beauty of a true economic buyer with a trusting relationship is that his or her word is golden. So start mining. Otherwise, you’re going to meet the lawyers.  

Notes 

1. You don’t negotiate terms if you can help it, but there is the option for full pay- ment on acceptance and a 10 percent discount. 

2. For those interested, of the 80 percent accepted, Option 1 is taken 25 percent of the time, Option 2 about 25 percent, and Option 3 about 50 percent.

3. If you can’t make it, ask about Thursday or even Saturday. These people wouldn’t be brought together for a single day, and your buyer may have simply chosen the best time for his or her schedule, but it probably could be altered.